Buying a Mobile Home
What to Expect After Your Offer Is Accepted on a Mobile Home in San Diego
What to Expect After Your Offer Is Accepted on a Mobile Home in San Diego After your offer is accepted, track the escrow deadlines and complete each step needed to buy the mobile home. Send requested documents to your agent, escrow, and lender promptly. If the home is in a park, go to park management […]
After your offer is accepted, track the escrow deadlines and complete each step needed to buy the mobile home. Send requested documents to your agent, escrow, and lender promptly. If the home is in a park, go to park management for the current space rent, written rules, utility information, and residency application and approval requirements for that home and space.
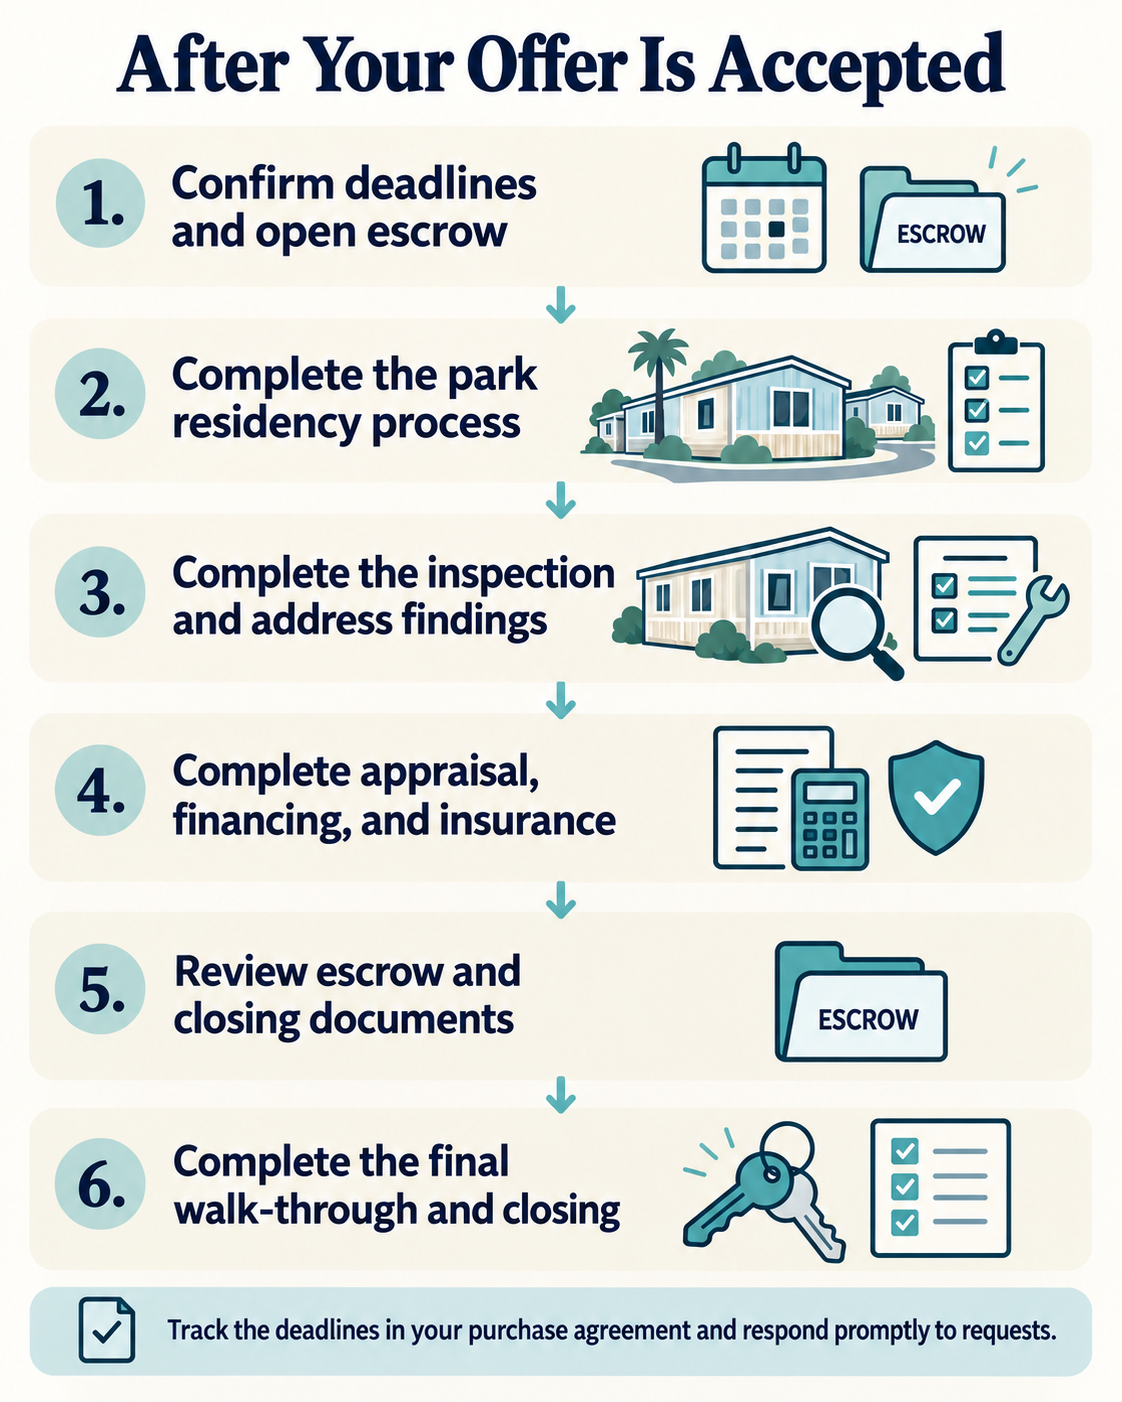
Schedule an inspection with a qualified inspector familiar with manufactured homes. Review the inspection findings and address any repair or price negotiations under your purchase agreement. If your financing requires an appraisal, complete that step and continue working with your lender. As part of the financing process, review and accept the insurance quote required for the loan. Before closing, review the final escrow and lender documents and complete a final walk-through of the home.
Start With Your Accepted Mobile Home Offer
After the seller accepts your offer, begin the park approval process and confirm your financing, inspection, and closing requirements.
Park applications may request financial information, identification, a background check, age-related information for an age-restricted community, or other information used in the park’s screening process. Ask the park manager for the specific requirements that apply to the community.
Arrange an inspection of the mobile home with an inspector familiar with manufactured-home construction. The inspector can check the structure, support system, plumbing, electrical system, and other accessible components.
Review your purchase agreement’s contingencies and deadlines so you understand what must happen for the sale to proceed and what options the agreement gives you if an issue arises.
Gather the income, asset, credit, and other documents your lender requests, and continue the financing process.
Before closing, review the expected loan, escrow, insurance, and other transaction costs that apply. For a park home, also confirm the current space rent, separately billed utilities, and other recurring park charges with park management. You can use the SD Mobile Home Guide affordability calculator as an educational budgeting tool to see how those housing costs may fit your budget.
Confirm Deadlines and Open Escrow
Check your purchase agreement for deadlines to open escrow and complete inspections, appraisals, financing, park approval, and other contingencies that apply to your transaction.
These dates determine when you must act and can affect whether the sale proceeds under the agreed terms.
Escrow holds funds and documents while the transaction’s conditions are completed.
Confirm the deadlines with your agent and escrow officer, and ask them to explain anything unclear.
Send requested documents, such as proof of funds and required disclosures, promptly, and contact the appropriate transaction professional if an issue could affect a deadline.
Get Park Residency Approval in Writing
If the home is in a mobile-home park, complete the park’s residency application and approval process before completing the purchase. Follow your purchase agreement for the timing of any park-approval contingency or other contingency decisions.
Park management may request information about your financial ability to pay the park rent and charges, identification, a background check, prior tenancy information, age-related information for an age-restricted community, or other information permitted as part of its screening process. Ask management for the current written requirements rather than relying on a general income multiple or another park’s standards.
Request written confirmation of the park’s decision and keep it with your transaction records.
If anything about the approval is unclear, ask the park manager and your agent or transaction professional before you proceed.
Schedule a Mobile Home Inspection and Address the Findings
Schedule an inspection after the seller accepts your offer and within the inspection period in your purchase agreement. A qualified inspector can assess the mobile home’s condition before closing and identify issues that may need further evaluation or repair.
Choose an inspector familiar with manufactured-home construction and ask them to examine the support system, marriage line when applicable, plumbing, electrical system, roof, and other accessible components.
When you receive the report, review the findings with the inspector and ask which concerns are urgent, which may need a specialist, and which can be planned for later.
If the report identifies needed repairs, use the documented findings to discuss repairs, a price adjustment, or other terms with the seller, subject to your purchase agreement. Put any agreed changes in writing.
Any repairs the seller agrees to complete can be checked again during the final walk-through before closing.
Review the Mobile Home Appraisal
If your lender requires an appraisal, the appraisal estimates the home’s value for the financing decision. The appraiser may consider comparable manufactured-home sales, the home’s age and condition, and other characteristics relevant to the appraisal.
Review the appraisal report for the estimated value and any conditions or concerns noted for the loan. If the appraised value is below the purchase price, ask your lender and agent about the options available under your financing and purchase agreement.
Keep the appraisal separate from the home inspection: an appraisal is primarily a valuation for the lender, while the inspection is intended to evaluate the home’s condition in more detail.
Complete Financing and Insurance
After your offer is accepted, continue the financing process for the type of manufactured home and site arrangement you are buying.
For an existing home in a mobile-home park, ask the lender whether it finances used manufactured homes on rented or leased spaces and what home, park, or site documents it needs. Home-only or personal-property financing may be available for some park homes.
If the manufactured home is sold with owned land, mortgage financing may be available when the property and borrower meet the lender’s and loan program’s requirements. Some government-backed manufactured-home programs can also apply to homes on leased lots, so do not assume land ownership by itself determines the available loan type.
Provide the income, asset, credit, and property information the lender requests. Park residency approval is a separate process from lender underwriting, although the lender may request park or site documents for the loan.
As part of the financing process, you will receive an insurance quote to review and accept. The required insurance coverage needs to be in place for the lender to complete the financing, so respond promptly to any insurance documents or requests connected with the loan.
Review Escrow and Closing Documents
As the transaction moves toward closing, escrow coordinates the ownership-transfer paperwork, including the title and registration transfer, and lets you know which documents or signatures are required from you.
You do not need to independently clear the title or manage the seller’s title and registration. Respond to requests from escrow and ask the escrow officer or your agent about anything you do not understand.
Review the final lender and escrow documents, including the charges and terms that apply to your transaction, before signing.
Complete the Walk-Through and Close
Before closing, walk through the mobile home and confirm it is in the agreed condition. If the seller agreed to complete repairs after the inspection, check that those items have been addressed.
Check the status of the purchase agreement’s contingencies, including park approval, inspection, and financing when applicable.
Review the final lender and escrow documents and ask about any charge or term you do not understand before signing. If your loan uses a Closing Disclosure, review that document as part of the process.
Make sure the required insurance coverage is in place and that you know the amount and method required for any funds due at closing.
Sign the documents required to complete the purchase. Escrow handles the title and registration transfer as part of the closing process. Possession and delivery of the keys should follow the timing stated in your purchase agreement and closing instructions.
Conclusion
After your offer is accepted, track each deadline and respond promptly to requests. Get the current park information and complete the residency-approval process, arrange the mobile home inspection, address any inspection-related negotiations, and complete the appraisal, financing, and required insurance steps.
Escrow handles the title and registration transfer as part of closing. Review the final lender and escrow documents, complete the walk-through, confirm any agreed repairs have been addressed, and follow the closing and possession instructions for the transaction.