Financing, Costs & Ownership
Can You Finance a Manufactured Home in a San Diego Mobile Home Park?
Can You Finance a Manufactured Home in a San Diego Mobile Home Park? Yes, you may be able to finance an existing manufactured home in a San Diego mobile home park even if you don’t own the land. A lender may offer a chattel loan, which uses the home as collateral rather than the land. […]
Yes, you may be able to finance an existing manufactured home in a San Diego mobile home park even if you don’t own the land. A lender may offer a chattel loan, which uses the home as collateral rather than the land. Financing options and requirements vary by lender, home, transaction, and park.
When working with a mobile home sales agent, the agent can coordinate much of the financing-related process, including home information, connections with lenders that finance used park homes, purchase documents, and communication with the seller, escrow, and park management. The buyer generally reviews and accepts an offered lender and loan option, provides personal financial information, completes the park’s personal residency application or screening requirements, and signs lender documents. SD Mobile Home Guide is not a lender or underwriter. For help exploring homes for sale, visit SD Mobile Home Guide.
Can You Finance a Home in a San Diego Park?
You may be able to finance a manufactured home in a San Diego park, but financing can differ from a home sold with land. In a typical park transaction, you are buying an existing home already located in the community while leasing the space beneath it.
A mobile home sales agent can help provide the home’s identifying information and condition details and connect buyers with lenders that finance used manufactured homes in parks. Financing is often arranged through 21st Mortgage in the agent-assisted workflow described here, although other lenders and options may be available depending on the transaction.
The lender determines its financing requirements and reviews the buyer’s personal financial information. The buyer reviews the offered financing arrangement and decides whether to accept the lender and loan terms.
After you have a fully accepted offer, the agent can help coordinate the current space rent, written rules, rental or lease information, and residency requirements with park management. The buyer completes any personal application, screening information, or signatures requested by the park.
Which Loans Fit Manufactured Homes on Rented Lots?
A chattel loan may finance a mobile home on a rented lot without using the land as collateral. This type of financing generally applies when the manufactured home is titled separately from the land.
Loan options and terms depend on the lender, home, park, and transaction. Traditional real-property mortgages may not fit a home-only purchase because those loans commonly involve the home and land together.
Some government-backed financing programs may be available when their requirements are met. A mobile home sales agent can help connect buyers with lenders that finance used park homes and coordinate the home-related information those lenders request.
The buyer reviews the lender and loan option offered for the home, including the financing terms and required personal documentation.
What Down Payment and Loan Terms Can You Expect?
Down payment requirements, interest rates, repayment terms, and fees depend on the lender, home, park, and financing program.
The lender will request the personal financial information needed to evaluate the buyer’s application. This may include income, assets, debts, identification, and available funds. The mobile home sales agent can coordinate the home and transaction information separately.
Chattel loans can have different repayment periods and interest rates, so buyers should understand the full terms of the offered financing arrangement before accepting it.
Review the down payment, monthly loan payment, interest rate, repayment term, fees, and any prepayment provisions.
Space rent is separate from the home’s loan payment and should be included when evaluating the total monthly housing cost.
To compare the home payment with space rent and other expected housing expenses, use the SD Mobile Home Guide affordability calculator as an educational budgeting tool. It does not determine lending decisions or loan terms.
How Do Age and Condition Affect Financing?
A mobile or manufactured home’s age and condition can affect the financing options available. Requirements vary by lender, financing program, home, and transaction. A lender may request an inspection, appraisal, or other documentation concerning the home.
The mobile home sales agent can help provide or confirm the home’s make, model, year, serial number, condition, and available identifying information. HUD certification or data-plate information may also be requested when applicable.
Some financing programs have requirements related to the home’s age, construction standards, condition, or valuation. The lender determines whether the specific home meets its requirements.
Problems with the roof, plumbing, electrical system, structure, or other components may lead to additional documentation or repair requests. An appraisal or valuation may also affect the financing amount a lender is willing to offer.
When the lender identifies a concern involving the home, the mobile home sales agent can help coordinate the requested information with the seller and other transaction participants.
How Do Park Rules and Space Rent Affect Financing?
Park residency and home financing are separate parts of the transaction. However, a lender may need information about the park’s rental or lease arrangement before completing the financing process.
After a fully accepted offer, the mobile home sales agent can help coordinate the current space rent, written rules, rental or lease information, and residency requirements for the specific home and space with park management.
The buyer completes the personal portions of the park’s residency application and screening process directly with management. In the agent-assisted workflow described here, this is generally handled before the buyer signs the final lender documents, although the timing of particular lender forms can vary.
Space rent also affects the buyer’s monthly housing budget. The agent can help explain the current space rent separately from the loan payment so the buyer understands both expenses.
Requirements vary by park, home, transaction, and lender. The agent helps coordinate the home and park information while the lender handles its financing review and park management handles the residency process.
How Does Your Agent Coordinate Park Home Financing?
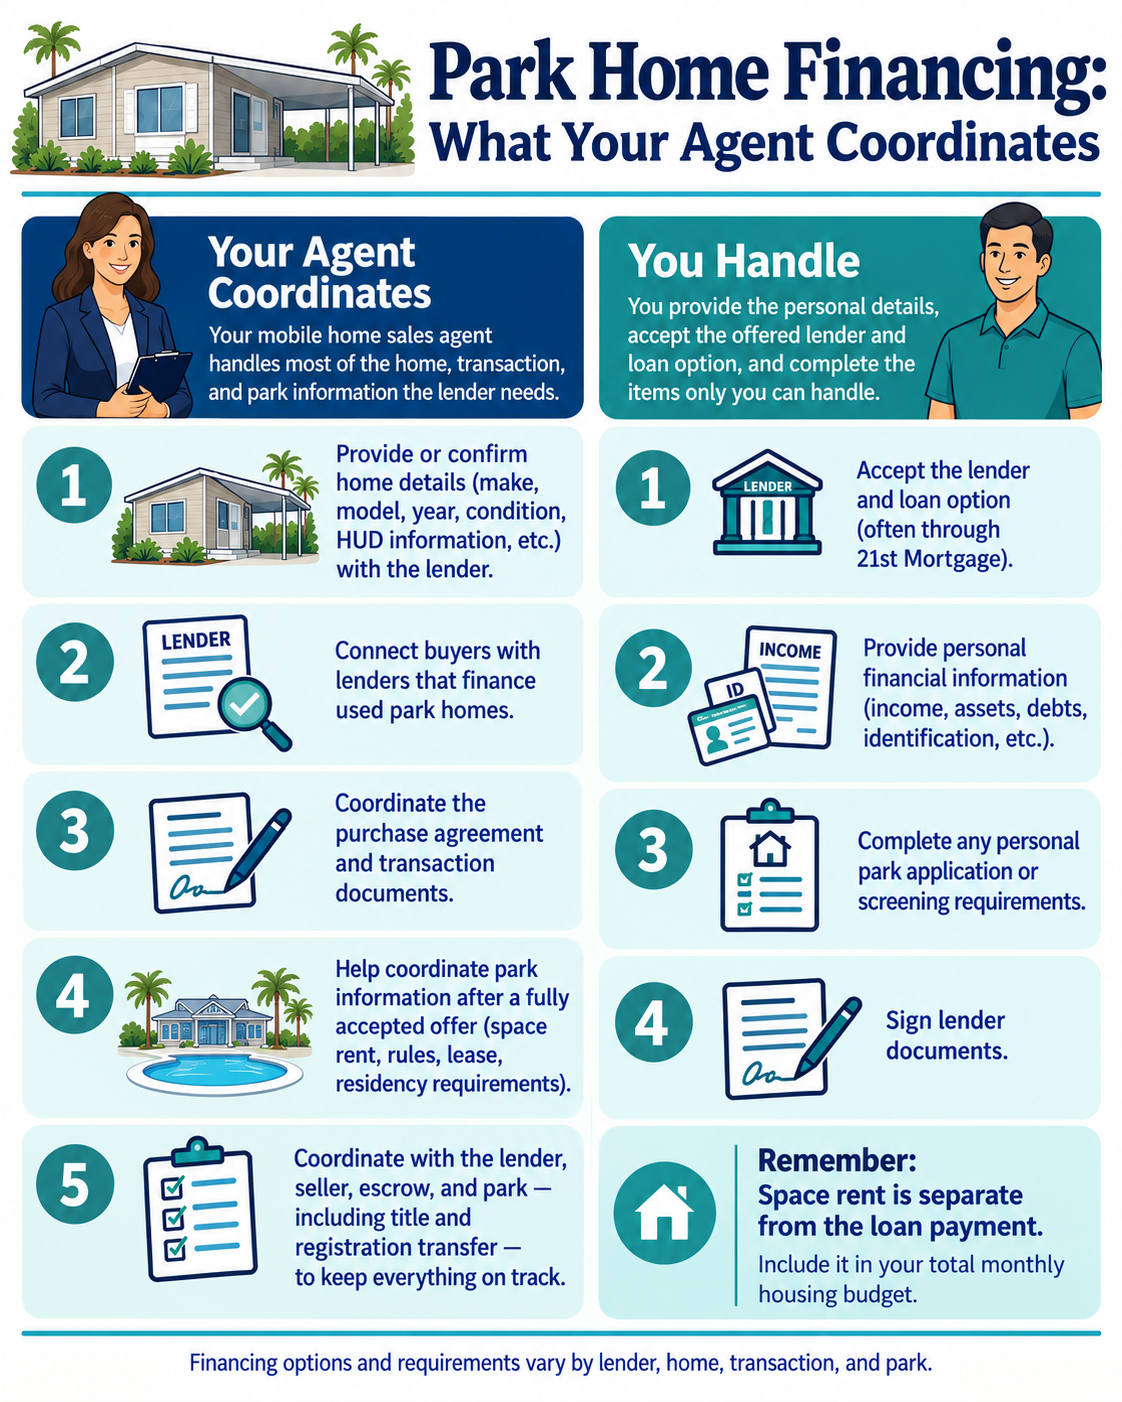
In a transaction handled by a mobile home sales agent, the agent coordinates much of the home, transaction, and park information needed for financing. The buyer handles the personal information and required actions that only the buyer can complete.
The agent generally begins by providing or confirming the home’s identifying information, including its make, model, year, serial number, condition, and available HUD information when applicable. The agent can then help connect the buyer with lenders that finance used park homes.
The agent coordinates the purchase agreement and other transaction documents needed for the financing process.
After a fully accepted offer, the agent can help coordinate access to the current space rent, written rules, rental or lease information, and residency requirements directly from park management.
Throughout the transaction, the agent works with the lender, seller, escrow, and park management to help keep the necessary documents and information coordinated. This includes confirming that the seller’s title and registration are ready for transfer and helping coordinate those documents through escrow or the applicable transfer process. The buyer is not expected to take possession of the original title and registration during this process.
The buyer’s responsibilities generally include reviewing and accepting the offered lender and loan option, supplying requested personal financial information, completing the personal park residency application or screening requirements, and signing the required lender documents.
Although specific lender and transaction procedures can vary, this agent-assisted approach helps keep the home and transaction coordination separate from the buyer’s personal responsibilities.
Conclusion
You may be able to finance an existing mobile or manufactured home in a San Diego park even when the land is not included in the purchase. Available financing depends on the home, lender, transaction, and financing program.
When working with a mobile home sales agent, the agent can help coordinate home details, lender connections, purchase and transaction documents, park information after a fully accepted offer, and communication with the seller, lender, escrow, and park. Title and registration are handled as part of the transaction and transfer process.
The buyer generally reviews and accepts the offered financing arrangement, provides personal financial information, completes the personal park residency application or screening requirements, and signs lender documents.
Remember that space rent is separate from the loan payment and should be included in the total monthly housing budget. SD Mobile Home Guide is not a lender or underwriter. To explore homes for sale, visit SD Mobile Home Guide.